
Table of Contents
- Market Context
- What Happened
- Why It Matters
- Sector Breakdown
- Risks to Watch
- What to Watch Next
- Final Outlook
Market Context
The TSXV small-cap and penny stock universe begins the week of September 22 in an environment shaped by three compounding macro forces that landed over the past week. The Federal Reserve’s September 16 unanimous rate hike to 3.75%–4.00% — with a dot-plot showing 16 of 18 participants expecting at least one more 2026 increase — has sustained the real yield pressure on gold that has been the precious metals sector’s most persistent headwind. The TSX fell 0.2% on Friday September 18, with Agnico Eagle losing 1.1%, Barrick shedding 1.5%, and WPM falling 1% even as gold prices remained firm — a “wrong-way” pattern where gold held but gold mining equities declined on bond yield pressure and profit-taking after Thursday’s brief rally. And on September 21, Trump announced he is working on a “massive deal” to purchase potash from Belarus — a geopolitical manoeuvre directly targeted at undermining Canada’s potash leverage in the trade war, which had been discussed among premiers as a potential retaliatory tool.
For TSXV penny stock investors, the potash angle deserves specific attention. If Trump successfully secures a large-scale Belarusian potash supply — bypassing the Canadian producers that hold approximately 30–40% of global potash reserves — one of Canada’s most strategically significant commodity leverage tools in the trade war would be partially neutralised. Nutrien (TSX:NTR), Saskatchewan’s potash producers, and the broader prairie agricultural economy would face a long-term competitive headwind from a diversified U.S. supply base. That development, while not immediate in its market impact, alters the medium-term potash pricing outlook in ways that affect junior potash explorers and fertiliser-adjacent TSXV names.
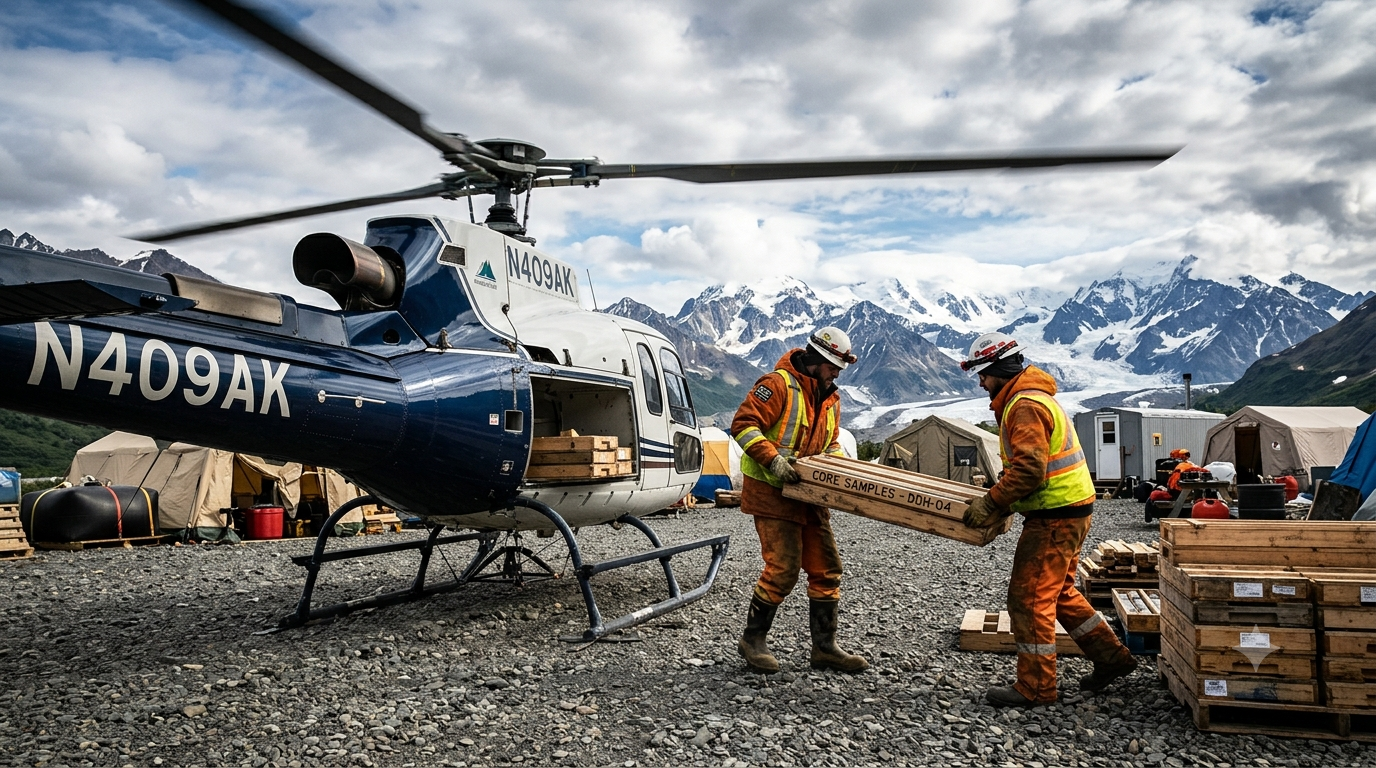
Despite this backdrop, the TSXV’s most analytically interesting stories remain company-specific and independent of the broader macro complex. Freegold Ventures (TSXV:FVL) continues advancing its helicopter-supported Phase 1 drill programme at the Munro Lake-adjacent target within its Golden Summit project in Alaska, targeting higher-grade gold corridors toward the Pre-Feasibility Study that remains the project’s milestone catalyst. At CA$670 million market cap and zero debt, Freegold occupies the strongest balance sheet position in the Alaskan junior gold exploration universe — a characteristic that has never been more important than in a rising rate environment where the cost of equity capital for pre-revenue companies has increased substantially.
Also Read: Safe investments for new investors
What Happened
On Friday September 18 and through Monday September 21, the TSXV small-cap mining complex absorbed continued rate-pressure selling after the Fed hike, with gold mining names across the size spectrum extending modest losses. The TSX Materials sector fell alongside the broader index, consistent with the post-hike adjustment process that the March 2026 pattern had anticipated. Trump’s September 21 announcement of a potential Belarus potash deal introduced a new geopolitical variable into the Canadian resources story — one that specifically targets the agricultural commodity that Canadian premiers had been discussing as a trade war leverage tool. Bank of Canada Governor Tiff Macklem, speaking in Halifax on September 21, stated that U.S. trade policy unpredictability “could set back the recent progress by the Canadian economy,” providing the most direct BoC acknowledgement of the trade war’s economic damage in recent weeks. Freegold Ventures’ active drill campaign at Golden Summit continues as a company-specific catalyst independent of these macro developments, and investors are watching for assay results from the current programme.
Why It Matters
Belarus Potash Changes the Trade War’s Commodity Leverage Landscape
Trump’s announcement of a potential Belarus potash deal is analytically significant beyond its immediate market impact. Canada had been positioned — through premiers’ discussions — to use its dominant global potash supply as a negotiating tool: restricting exports to U.S. agricultural markets would create pain for American farmers while demonstrating Canada’s commodity leverage. If Belarus potash becomes a credible U.S. alternative supply, that leverage is weakened. For TSXV-listed fertiliser and agricultural chemistry stocks, this signals a more competitive medium-term pricing environment. For the broader trade war narrative, it demonstrates that the Trump administration is actively working to reduce commodity dependencies on Canada — a strategic pattern that investors in Canadian resource junior companies should monitor carefully.
Gold’s “Firm Prices but Falling Stocks” Pattern Signals Technical Adjustment, Not Fundamental Deterioration
Friday’s pattern — gold prices firm but gold mining stocks falling — is a specific technical signal that experienced resource investors recognise. When the commodity holds but the equities decline, the driver is typically sector rotation out of mining equities (profit-taking, rebalancing, institutional de-risking) rather than commodity-level fundamentals changing. That pattern can create entry points for investors who identify quality names with active operational catalysts. Freegold Ventures — with its debt-free balance sheet and active 2026 drill programme — fits that profile: operationally advancing, fundamentally unchanged, and potentially less expensively priced than a week ago purely due to sector-level adjustment.
Sector Breakdown
The TSXV penny stock universe on September 22 divides along familiar post-hike lines. Gold explorers with active programmes — Freegold Ventures at Golden Summit, Wescan Goldfields at Munro Lake — are the most defensible sub-category through rate pressure because their value derives from geological discovery potential and management execution rather than near-term free cash flow that gets discounted at higher rates. Copper and critical minerals names — benefiting from the structural AI electrification and energy transition demand narrative — provide a second investment sub-theme that is partially insulated from gold’s specific rate-hike yield competition headwind. Potash and agricultural resource names face the newly introduced Belarus supply competition risk. TSXV blockchain and AI-adjacent names — HIVE Digital Technologies — navigate the dual macro environment of cryptocurrency price sensitivity and AI sector uncertainty from the “pace the frontier” commentary of earlier in September.
Risks to Watch
The October Fed hike — at elevated probability following the September 16 dot-plot — remains the most acute near-term risk for gold-linked TSXV names, as an additional 25-basis-point move to 4.00%–4.25% would push real yields higher and compress gold further. Belarus potash represents the most specific new risk for agricultural resource names, though the deal’s timeline and actual supply scale are unknown. TSXV liquidity risk is ever-present and is amplified in rate-pressure environments when institutional investors reduce speculative allocation. The September 29 tariff expansion effective date introduces a diffuse economic headwind that affects overall investor confidence in Canadian assets.
What to Watch Next
Freegold Ventures’ assay results from the current drill programme at Golden Summit are the most important company-specific watchpoint. Any detail on the Belarus potash deal — supply volume, timeline, pricing terms — will clarify whether Nutrien and junior potash names face a meaningful competitive shift or a negotiating tactic with limited commercial substance. The October FOMC meeting and economic data between now and then will determine whether additional rate pressure materialises. Gold price action relative to US$4,300 — the level that began serving as near-term support following the Fed hike — will be the commodity-level signal investors should monitor daily.
Final Outlook
The TSXV penny stock universe enters September 22 with more macro headwinds than it faced a month ago — higher real yields, a strengthening U.S. dollar, and now a specific geopolitical threat to one of Canada’s commodity leverage positions through the Belarus potash announcement. Within those headwinds, the investment case for quality junior miners with active programmes, debt-free balance sheets, and company-specific geological catalysts remains analytically intact. The discipline to separate macro-driven price pressure from fundamental deterioration is more important than ever in this environment.
Verdict: Watchlist candidate, not a broad buy signal. Debt-free gold explorers with active drill campaigns (Freegold Ventures) remain the most defensible TSXV positions. Monitor October FOMC probability and Belarus potash deal details as the two most consequential near-term variables for the penny stock resource universe. Company-specific assay results provide the most reliable catalyst for individual position action.
Sign Up For our Newsletters to get latest updates