
Table of Contents
- Market Context
- What Happened
- Why It Matters
- Sector Breakdown
- Risks to Watch
- What to Watch Next
- Final Outlook
Market Context
Canada’s electric vehicle sector enters the week of October 5 with a convergence of macro and sector-specific tailwinds that is more genuinely constructive than any configuration it has faced since early in the Canada-U.S. trade war’s escalation. The soft U.S. September non-farm payrolls — released Friday October 2 — have cut Federal Reserve rate-hike bets, reducing the discount rate headwind that has been compressing long-duration growth equity valuations through September. Asian markets surged Monday in response, and the global risk-on repricing is supporting the growth stock categories — including EV infrastructure manufacturers — that benefit most from lower discount rate environments. That macro shift arrives precisely when Canada’s EV sector’s most powerful commercial tailwind is also strengthening: diesel prices at historic highs.
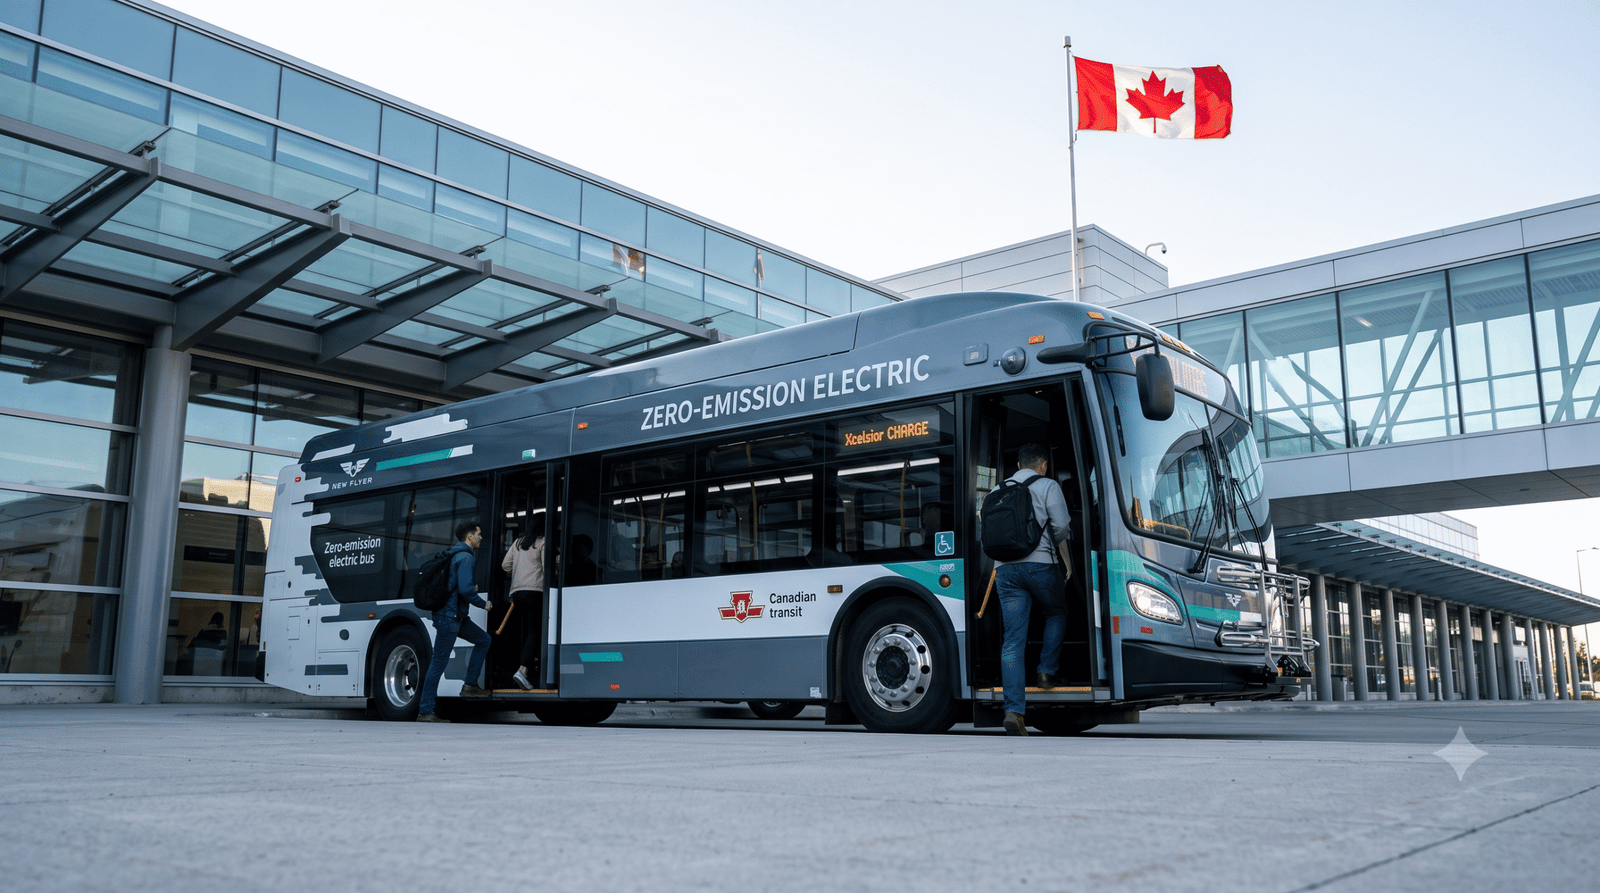
BNN Bloomberg’s September 29 confirmation that diesel prices are “on a big upward swing, rising to historic levels over the past month and filtering through to all corners of the economy” is the EV sector’s most powerful long-term commercial catalyst available. For transit agencies — which represent NFI Group’s (TSX:NFI) primary institutional customer base — diesel price spikes directly improve the total cost of ownership comparison between conventional diesel buses and zero-emission electric alternatives. When a transit agency’s finance committee models a new fleet procurement over a 12-year operating life, the fuel cost projection is one of the most important variables. At historic diesel levels, the fuel savings from electric buses over their operating life increase significantly, shortening the payback period on the higher upfront capital cost of EV procurement and making the business case for immediate fleet electrification compelling in a way that moderate diesel prices do not.
NFI Group’s record CA$13.7 billion backlog — accumulated through years of contract wins including the East Colfax BRT project (September 8) and Alexander Dennis’s 207-bus Liverpool City Region win (September 4) — provides the most direct financial evidence that transit agencies globally are already acting on that fleet electrification calculus. A CA$13.7 billion backlog represents years of contracted revenue from institutional customers — municipal transit authorities, national rail systems, and government fleet operators — who have made binding commitments to zero-emission procurement on timelines that diesel price fluctuations can accelerate but that are structurally driven by net-zero transportation targets that are independent of the current trade war and rate cycle.
What Happened
In the sessions leading into today’s October 5 open and throughout this morning’s session, the macro environment has shifted constructively for Canadian EV stocks. The soft U.S. September jobs data — which cut Fed hike bets and sparked Asian markets to rise strongly on October 5 — reduces the discount rate applied to NFI Group’s long-duration contracted revenue stream. When the October FOMC hike probability declines, the present value of NFI’s CA$13.7 billion backlog improving mechanically even without any new contract announcement. Diesel prices sustaining at historic highs — filtering through to every transportation-related industry across Canada — reinforces the commercial urgency of fleet electrification for transit agencies and commercial vehicle operators who face budget pressure from elevated fuel costs. Celestica (TSX:CLS) is advancing 3.89% to CA$551.69 today, reflecting the same macro tailwind benefiting growth names broadly. The EV-adjacent Bell Canada-Cisco sovereign AI infrastructure announcement from September 29 — which positions Canadian telecommunications as the backbone for next-generation connected infrastructure — continues generating sector-level positive sentiment around Canadian companies that enable the digital transformation of transportation systems, including EV fleet management.
Why It Matters
Diesel at Historic Highs Is the EV Sector’s Most Durable Commercial Catalyst
The structural argument for fleet electrification does not depend on any single diesel price spike. It depends on the expectation that diesel prices will remain elevated or continue rising over a multi-decade operating horizon, while EV technology costs continue declining and charging infrastructure expands. What historic diesel prices do is dramatically shorten the timeline for that argument to become financially compelling for specific procurement decisions. A transit agency that was modelling fleet electrification over a 10-year horizon may now be modelling the same economics over a 5-year horizon because the fuel cost savings are larger at historic diesel levels. NFI Group — whose institutional customers are exactly these transit agencies — benefits directly from any acceleration in procurement timelines. The CA$13.7 billion backlog is the evidence that many agencies have already moved from modelling to contracting.
The Soft Jobs Data Provides Rate Relief at the Best Possible Moment for EV Infrastructure Financing
Municipal transit agencies finance new fleet procurements through debt — typically long-term municipal bonds or government capital budgets. When interest rates rise, the cost of that debt financing increases, slowing procurement approvals in budget-constrained agencies. The Fed’s September 16 rate hike and the prospect of an October follow-on had been creating exactly this headwind: higher borrowing costs for the agencies that purchase NFI’s buses. October 5’s soft-jobs-data-driven reduction in rate-hike bets provides the mirror benefit: lower expected financing costs make transit agency capital budget approvals for new zero-emission fleets more financially manageable, potentially accelerating the conversion of NFI’s existing backlog — and any new orders — through budget approval processes.
Sector Breakdown
Canada’s EV stock universe on October 5 organises around its established hierarchy with the week’s macro context adding specific nuance to each name’s near-term prospects. NFI Group is the sector’s institutional anchor — CA$13.7 billion backlog, diversified manufacturing across New Flyer, Alexander Dennis, MCI, and ARBOC, U.S. domestic manufacturing through New Flyer of America that provides tariff insulation, and European market access through Alexander Dennis that operates entirely outside the Canada-U.S. bilateral trade dispute. The soft jobs data benefits NFI through its effect on transit agency financing costs rather than through direct revenue impact. Electrovaya Inc. (TSX:ELVA) — the Mississauga-based lithium-ion battery technology company — provides the battery manufacturing angle that complements NFI’s bus systems integration. Electrovaya’s battery systems for EV and materials-handling applications benefit from the same diesel price tailwind that is accelerating NFI’s order timing, because warehousing and logistics operators who use electric forklifts and material-handling equipment also face historic diesel costs for their conventional equipment alternatives. TELUS Corporation (TSX:T) at CA$11.47 — down 1.38% today — is relevant to the EV sector as the wireless infrastructure provider whose networks will support connected and autonomous electric vehicle systems, though the stock’s –1.38% session confirms that its rate sensitivity is a near-term headwind even in today’s broadly risk-on session.
Risks to Watch
NFI Group’s most significant near-term risk from the September 29 tariff expansion on aluminum — one of the primary materials in transit bus body construction — is a real cost input concern that investors should not dismiss. If Canadian-manufactured aluminum faces higher costs from either direction of the bilateral tariff structure, NFI’s margins on Canadian-manufactured vehicles could be affected. The company’s U.S. manufacturing through New Flyer of America provides some insulation for its U.S.-market vehicles, but the Canadian manufacturing base used for some contracts may face incremental aluminum cost pressure. The rate relief from today’s soft jobs data — while genuinely constructive — is not a guarantee of an October FOMC hold: if subsequent October data (CPI, PPI, employment claims) shows re-acceleration, the hike probability could return quickly. Electrovaya’s small revenue base makes it more vulnerable to any slowdown in the EV fleet electrification adoption pace at specific key customers.
What to Watch Next
NFI Group’s next quarterly earnings release — which will include backlog conversion rates, delivery volumes, and the specific margin impact of any tariff-driven input cost increases — is the most important company-specific catalyst for the EV sector in October. Any formal announcement of Canada-U.S. trade progress following November 3’s U.S. midterm elections would be the sector-transforming policy development for NFI’s North American supply chain cost structure. The Bank of Canada’s October 28 rate decision will affect municipal transit agency financing costs and by extension the pace of fleet electrification procurement approvals. Diesel price trajectory — which is currently at historic highs and “filtering through to all corners of the economy” — will remain the most visible daily signal of whether the EV fleet electrification commercial urgency is building or moderating. Any Electrovaya commercial contract announcements with specific revenue contributions will be the battery technology sub-sector’s catalyst to monitor.
Also Read: Stock investment Canada for beginners
Final Outlook
Canada’s EV sector enters the week of October 5 with the most genuinely constructive combination of macro and commercial tailwinds it has experienced in months. The soft U.S. jobs data reduces rate-hike bets, lowering the discount rate on NFI’s long-duration contracted revenue stream and improving transit agency financing costs for fleet procurement. Diesel at historic highs sharpens the economic urgency of fleet electrification. NFI Group’s CA$13.7 billion backlog confirms that institutional transit customers have already made the binding procurement commitments that validate the sector’s commercial trajectory. Electrovaya’s battery technology provides the hardware complement to NFI’s systems integration. The Bell-Cisco sovereign AI infrastructure announcement extends the digital transformation narrative that will eventually encompass connected EV fleet management.
The near-term risks — tariff-driven aluminum cost pressure, rate-hike re-acceleration risk if jobs data proves to be a single-month anomaly, and the small scale of Electrovaya’s current revenue base — are manageable for investors with a 12-to-24-month horizon who understand the structural forces driving zero-emission fleet adoption. NFI Group’s institutional-scale backlog and geographic manufacturing diversification provide the most defensible EV sector position available on the TSX.
Verdict: Cautiously constructive. NFI Group’s CA$13.7 billion backlog, diesel-at-historic-highs commercial tailwind, geographic manufacturing diversification, and the week’s macro rate relief collectively provide the most compelling near-term EV investment case on the TSX. Monitor October earnings for tariff-related aluminum cost impacts and any new contract announcements that add to or sustain the record backlog. Electrovaya is a watchlist candidate for investors seeking early-stage battery technology exposure alongside NFI’s institutional-scale production franchise.
Sign Up For our Newsletters to get latest updates