
Table of Contents
- Market Context
- What Happened
- Why It Matters
- Sector Breakdown
- Risks to Watch
- What to Watch Next
- Final Outlook
Market Context
The Canadian energy sector’s most consequential geopolitical development since the initial Iran conflict in February 2026 arrived Tuesday afternoon: Iran reportedly offered to reopen the Strait of Hormuz within seven days if the United States takes initial steps to ease military pressure. That single diplomatic signal — conveyed through back-channels at the UN General Assembly in New York — sent oil prices down US$1.85 on the day to US$90.52 per barrel on the November crude contract, extending what is now a multi-session retreat from the US$104.95 intraday high reached on September 14 when the Saudi East-West pipeline closure and Hormuz attacks were compounding simultaneously. The energy sector has absorbed that oil price retreat with declining stocks: Canadian Natural Resources (TSX:CNQ) fell 2.2% on Tuesday and Suncor Energy (TSX:SU) shed 2.7% — among the TSX’s notable declines in what was otherwise a strong +326-point session.
The analytical tension at the heart of the energy sector on September 23 is straightforward: a Hormuz diplomatic resolution would be unambiguously negative for oil prices in the near term — potentially sending WTI toward the high-US$70s or low-US$80s — while simultaneously being constructive for the broader Canadian economy, financial sector, and Bank of Canada’s policy flexibility. When the energy-driven inflation that has been justifying Fed rate hikes and threatening Bank of Canada hikes is removed, the rate environment that has been suppressing bank and technology valuations improves. The net TSX effect is more positive than negative, which is why Tuesday’s session closed up 326 points even as energy names declined. But for Canadian energy investors specifically, the question is whether a Hormuz resolution removes the supply premium that has been the sector’s primary performance driver since the conflict began.
Bank of Canada Governor Macklem added a critical domestic dimension to this calculus on Monday, warning explicitly that U.S. tariffs could push Q4 growth below 1% and that future rate decisions “will need to balance slowing growth against surging energy costs stemming from the Iran conflict.” That framing is important: it confirms the BoC views energy costs and growth risk as competing forces in its monetary policy assessment. If Hormuz resolves and energy costs fall, the BoC’s balance shifts toward the growth-support side — potentially removing the risk of a Bank of Canada hike that has been a modest additional headwind for Canadian rate-sensitive sectors.
Also Read: Best long term Canadian stocks
What Happened
Canada’s main stock index rose over 300 points on Tuesday, helped by gains in basic materials and technology stocks, while U.S. markets posted mixed results. The S&P/TSX composite index was up 326.21 points at 36,335.61. The November crude oil contract was down US$1.85 at US$90.52 per barrel. Iran reportedly offered to reopen the Strait of Hormuz within seven days if the US takes initial steps to ease military pressure. The pullback in the oil rally lent support to credit-sensitive stocks. Energy shares fell, with Canadian Natural (-2.2%) and Suncor (-2.7%). In contrast with energy’s losses, RBC, TD Bank, and Scotiabank gained nearly 0.5% as lower oil improved the inflation and rate-hike outlook for credit-sensitive financial names. Agnico Eagle and Barrick gained about 1% despite the mixed gold environment. Prime Minister Carney spoke at the UN General Assembly in New York, stating that Canadian potash will continue to be a “strength of our economy” — an explicit reaffirmation of Canadian commodity leverage in the trade dispute.
Why It Matters
Iran’s Seven-Day Hormuz Offer Changes the Oil Price Calculus Permanently for September
Even if Iran’s Hormuz offer does not lead to an immediate ceasefire, the fact that it was made publicly and at the UN General Assembly — a forum with international witness — changes the oil market’s risk premium assessment. Markets had been pricing a binary Hormuz scenario: either military attacks continue (supply premium sustained) or a ceasefire is reached (supply premium removed). The seven-day conditional offer introduces a third scenario: a structured, conditional de-escalation with defined timelines and prerequisites. That middle scenario is actually more analytically complex than either binary extreme, because it implies oil prices may settle in a range that reflects partial de-escalation risk rather than the full supply premium of peak conflict.
The Energy-Versus-Banks Trade Is the TSX’s Most Important Allocation Choice This Week
Tuesday’s session illustrated the energy-versus-banks allocation trade with unusual clarity: energy fell sharply (CNQ –2.2%, Suncor –2.7%) while banks gained (RBC, TD, Scotiabank +0.5%) in the same session, driven by the same oil-price catalyst. Investors holding energy names as a geopolitical hedge must now weigh whether the Hormuz de-escalation removes their thesis, or whether the structural case for Canadian oil sands producers — record production, low break-even costs, Pacific export access through Trans Mountain — sustains earnings quality at WTI in the high-US$80s to low-US$90s. For most integrated producers and oil sands operators, the answer at US$90 WTI is affirmative: they remain highly profitable. The question is whether the stock market multiple adjusts downward to reflect the removal of the conflict premium.
Sector Breakdown
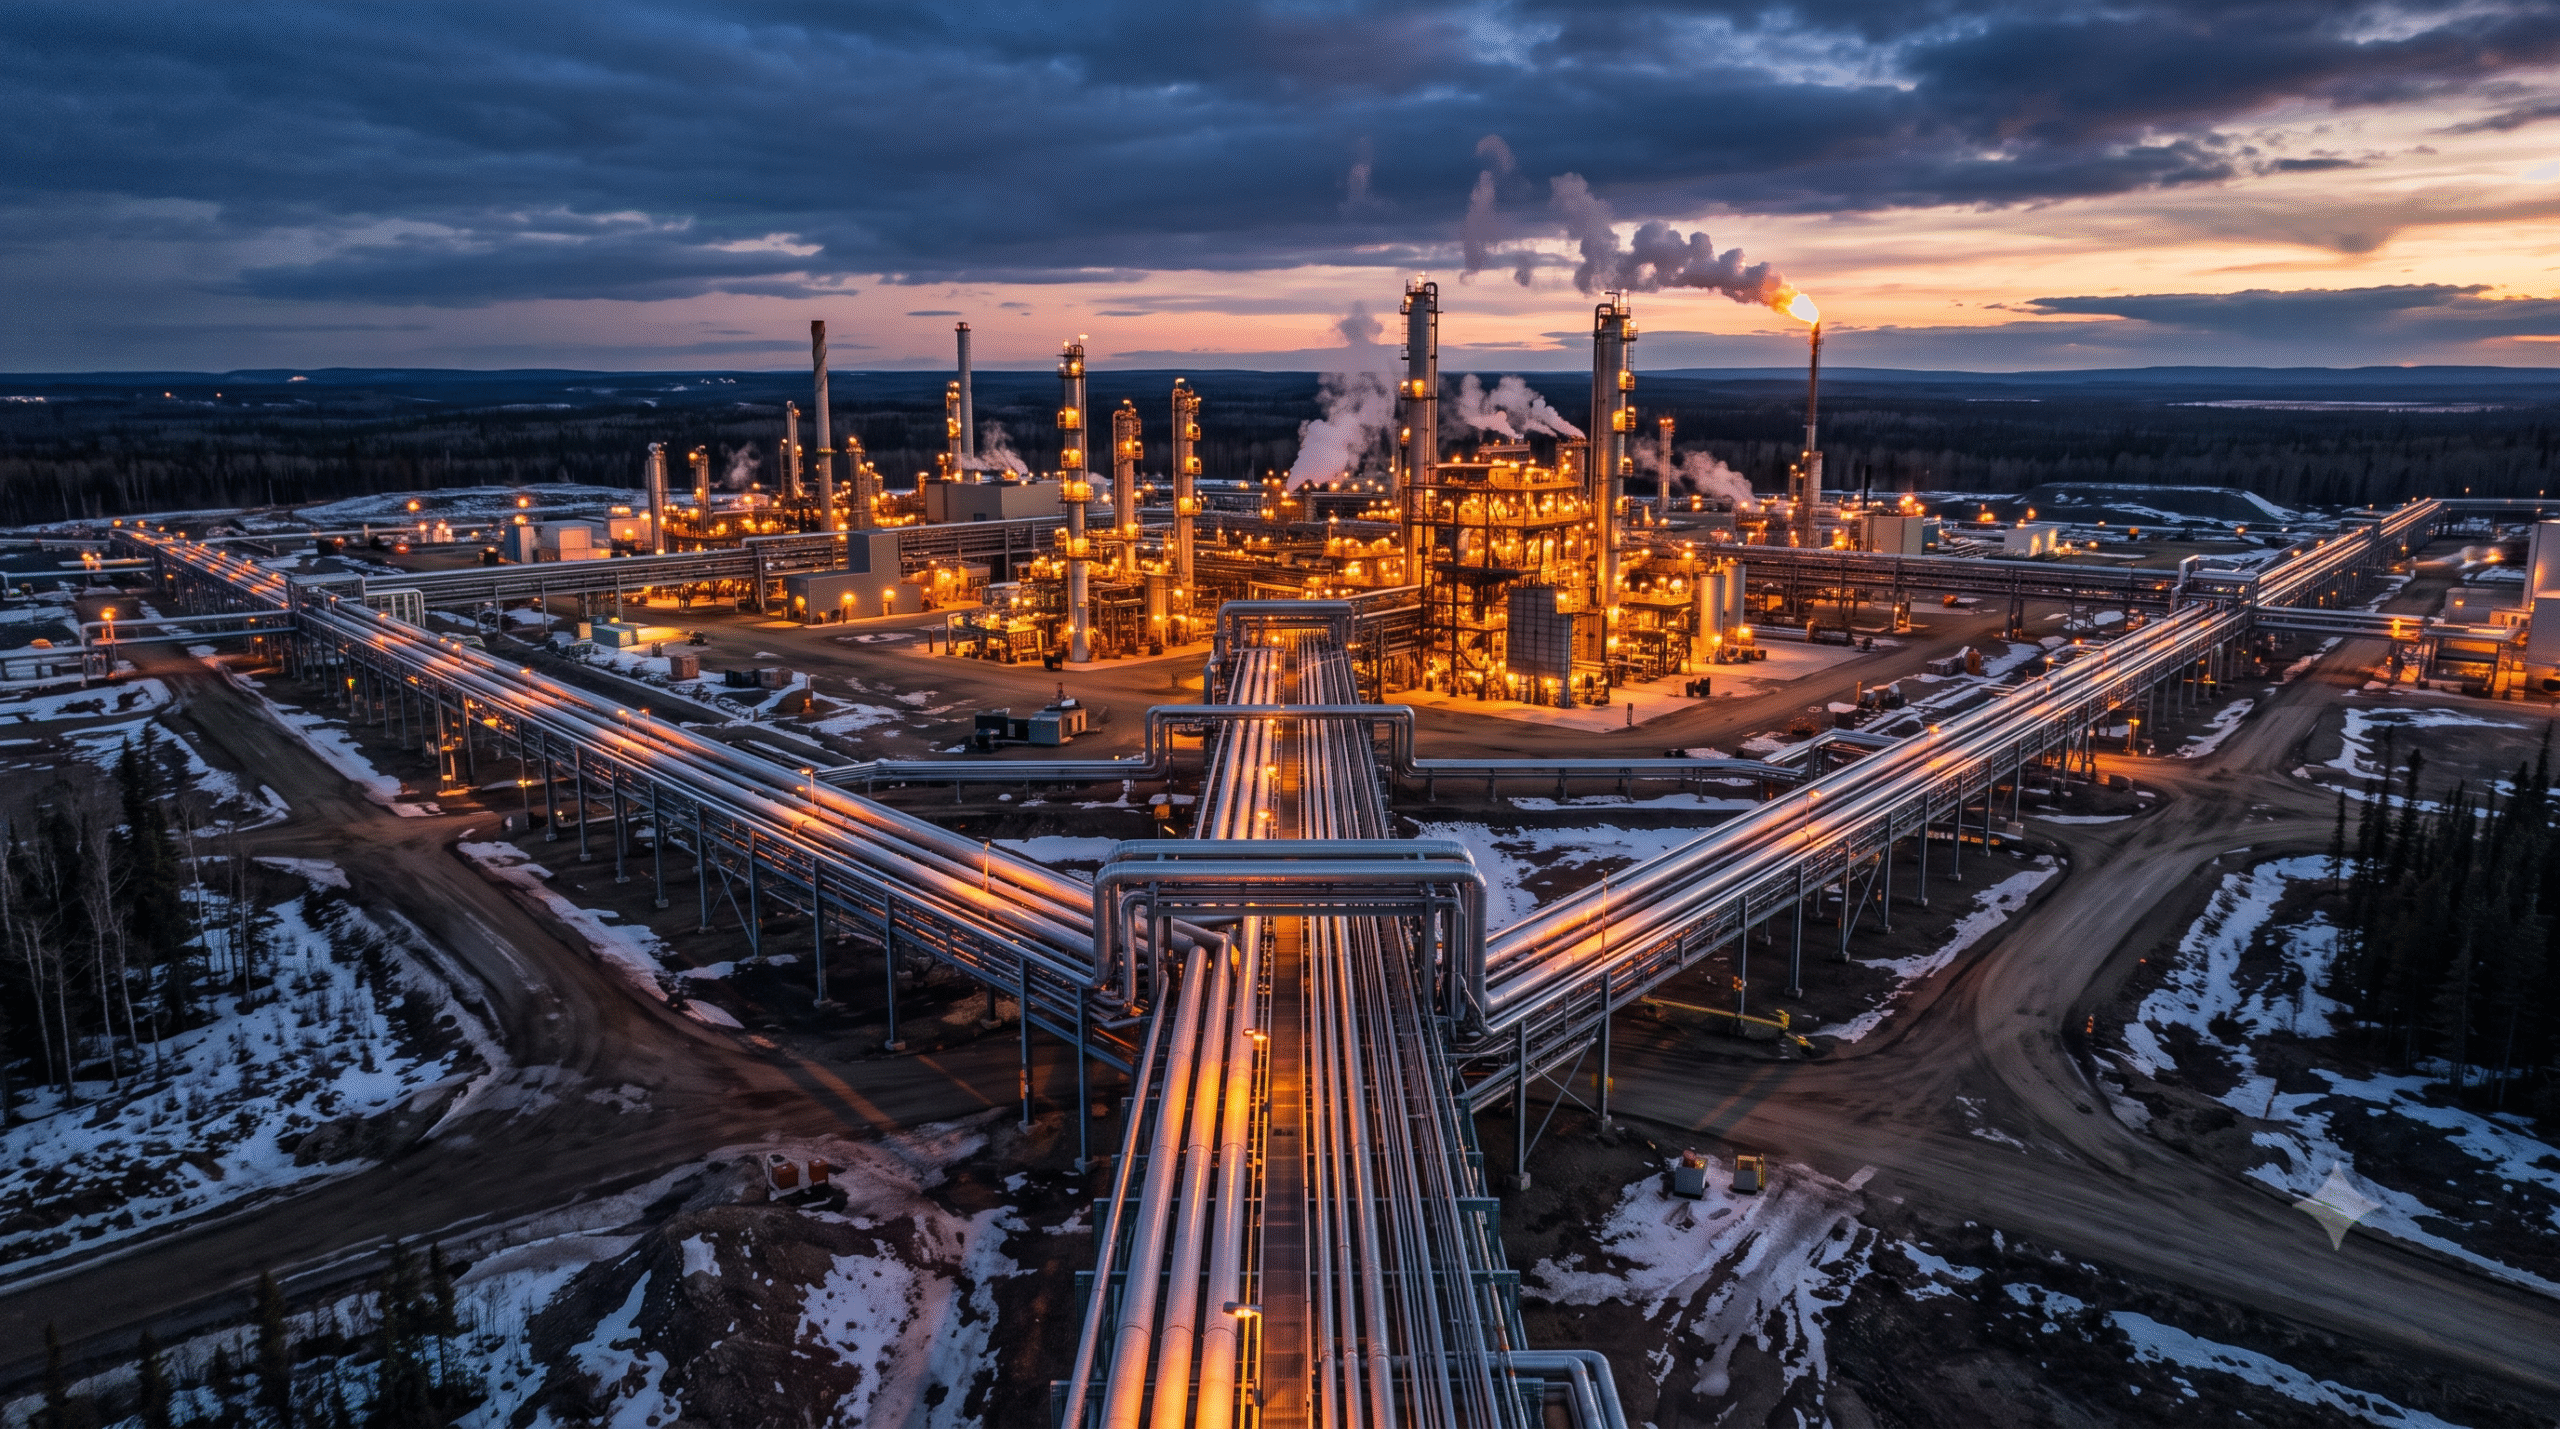
The Canadian energy sector on September 23 requires a more nuanced sub-sector analysis than it has in several weeks. Integrated majors — Suncor and Cenovus — carry the most resilience through oil price normalisation because their downstream refining segments benefit from lower crude input costs even as upstream revenues decline. At WTI near US$90, Suncor’s FCF yield remains strong. Pure-play oil sands producers — CNQ and Imperial Oil — are more directly sensitive to the directional WTI move but remain well above their break-even costs. Midstream infrastructure — Enbridge and TC Energy — are the week’s clearest beneficiaries of the oil price pullback: their regulated revenues are unaffected by commodity price, and lower oil reduces the bond yield competition that has been the most direct headwind to their income profile. If the Hormuz resolution reduces inflation expectations and lowers rate-hike odds, Enbridge’s 5.1% yield becomes more competitive relative to corporate bonds.
Risks to Watch
The primary risk for Canadian energy names is not a Hormuz resolution per se but the pace of resolution. If oil falls sharply to WTI below US$80 in the next two weeks — on a rapid peace settlement — Q3 earnings would still reflect the elevated prices of July, August, and early September, but Q4 guidance would need to be reset to a substantially lower price assumption. For investors holding energy names with expectations of continued high oil, that guidance reset would be the negative catalyst. The U.S. response to Iran’s Hormuz offer is the immediate unknown: Trump must take “initial steps to ease military pressure” per Iran’s condition, and whether those steps are forthcoming — and verifiable — is uncertain. The September 29 tariff expansion remains a domestic trade headwind independent of oil price direction.
What to Watch Next
The U.S. government’s formal response to Iran’s Hormuz offer — expected through UNGA diplomatic channels this week — is the energy sector’s most important near-term catalyst. Oil price action around US$90 WTI will signal whether markets believe the de-escalation is genuine or conditional. CNQ and Suncor Q3 earnings — expected in October — will provide the first comprehensive financial read on the summer oil price arc. Enbridge and TC Energy will be watched for whether the lower-oil, lower-rate-hike-risk environment begins to support their regulated income multiple expansion. The Bank of Canada’s October 28 decision — informed by whether energy inflation has eased — will be the domestic monetary policy response to the Hormuz situation’s resolution.
Final Outlook
Canadian energy stocks entered September’s second half as the TSX’s strongest performers, buoyed by Saudi pipeline closure and Hormuz attacks pushing WTI above US$100. Tuesday’s Iran Hormuz offer changes that narrative meaningfully. At US$90.52 WTI, the sector remains profitable and generating strong free cash flow — but the emergency supply premium that justified the extraordinary Q3 gains may be in the final stages of unwinding. The structural case — record production, low break-even costs, Pacific market access — remains analytically sound at prices well below the September peak.
Investors should reassess whether their energy positions were sized for the emergency premium or the structural fundamentals. The former thesis may be partially exiting with Hormuz diplomacy; the latter remains intact.
Verdict: Cautiously constructive on integrated producers and midstream at WTI near US$90. The structural investment case survives Hormuz de-escalation; the emergency premium does not. Monitor Iran-U.S. Hormuz diplomatic progress and Enbridge/TC Energy multiple recovery as the week’s energy-specific watchpoints.
Sign Up For our Newsletters to get latest updates