
Table of Contents
- Market Context
- What Happened
- Why It Matters
- Sector Breakdown
- Risks to Watch
- What to Watch Next
- Final Outlook
Market Context
Canada’s economy faces, this week, the most concentrated convergence of simultaneous structural pressures in 2026. Four forces are landing together with a precision that the Bank of Canada, Finance Canada, and Canadian corporate planning teams cannot address through a single policy lever: a Saudi East-West pipeline closure that has pushed WTI to US$101 and Brent to US$109, threatening to remove 4% of global supply for up to six weeks; a Federal Reserve rate hike at 87% probability on Wednesday that would raise U.S. rates above 4% and pull Canadian bond yields higher through rate differential pressure on the Canadian dollar; an AI industry self-regulation signal from Anthropic, OpenAI, and Musk that has triggered broad technology sector de-risking globally; and Canada-U.S. trade war escalation with September 29’s tariff expansion adding 50% duties on Canadian alcohol, dairy, wood, aluminum, and furniture just two weeks away.
None of these four forces, in isolation, is beyond Canada’s absorptive capacity. Together, they create a macro environment where the policy tools available to the Bank of Canada — rates, communication, emergency liquidity — are inadequate to address all four simultaneously. Governor Macklem has explicitly stated that monetary policy “cannot offset the effects of tariffs or global energy prices.” Yet those are precisely the two dominant economic forces this week. The Bank of Canada’s scheduled September 2 hold has already been made; the next scheduled decision is October 14. Between now and then, the Fed’s Wednesday hike will push Canadian bond yields higher regardless of the BoC’s posture, because markets will price the Canada-U.S. rate differential in the currency and bond markets independently of what Macklem says at his next press conference.
Canada’s GDP trajectory — which showed Q2 2026 growth of 3.3% annualised before any tariff impacts — is the economic foundation from which this week’s stresses are being absorbed. That foundation is genuine: employment was resilient through most of 2026, business investment surged 9.5% annualised in Q2, and the TSX’s year-over-year performance remains extraordinary at +21.9%. The risk is not that Canada’s economy is fundamentally weak; it is that the cumulative weight of these four simultaneous pressures could turn a manageable Q3 2026 economic slowdown into a sharper Q4 contraction than current consensus models project.
What Happened
On September 14, Houthi drone strikes forced the closure of Saudi Arabia’s East-West pipeline — which carries approximately 4 million barrels per day to the Red Sea port of Yanbu and provides a critical export bypass around Hormuz. Brent crude surged to US$109.80 intraday before settling at US$105.68. WTI reached US$104.95 before settling at US$101.39. Diesel prices hit all-time highs. Trump attributed the diesel surge primarily to the Russia-Ukraine war rather than Iran. The Oman meeting designed to manage Hormuz shipping tensions was postponed as Iran and Gulf state envoys failed to convene. Simultaneously, the AI safety commentary from Amodei, Altman, and Musk triggered broad selling across global technology markets: the South Korean Kospi fell 3.6%, the Nikkei fell 518 points to 63,492. Money markets confirmed 87% probability of a September 16 Fed rate hike. Gold fell US$57.00 to US$4,351.90. The Tickmill daily outlook characterised the macro environment as placing central banks with “limited room to cushion volatility” while “stretched equity multiples reduce the margin for disappointment.”
Why It Matters
The Saudi Pipeline Closure Changes Canada’s Energy Income Calculation for Six Weeks
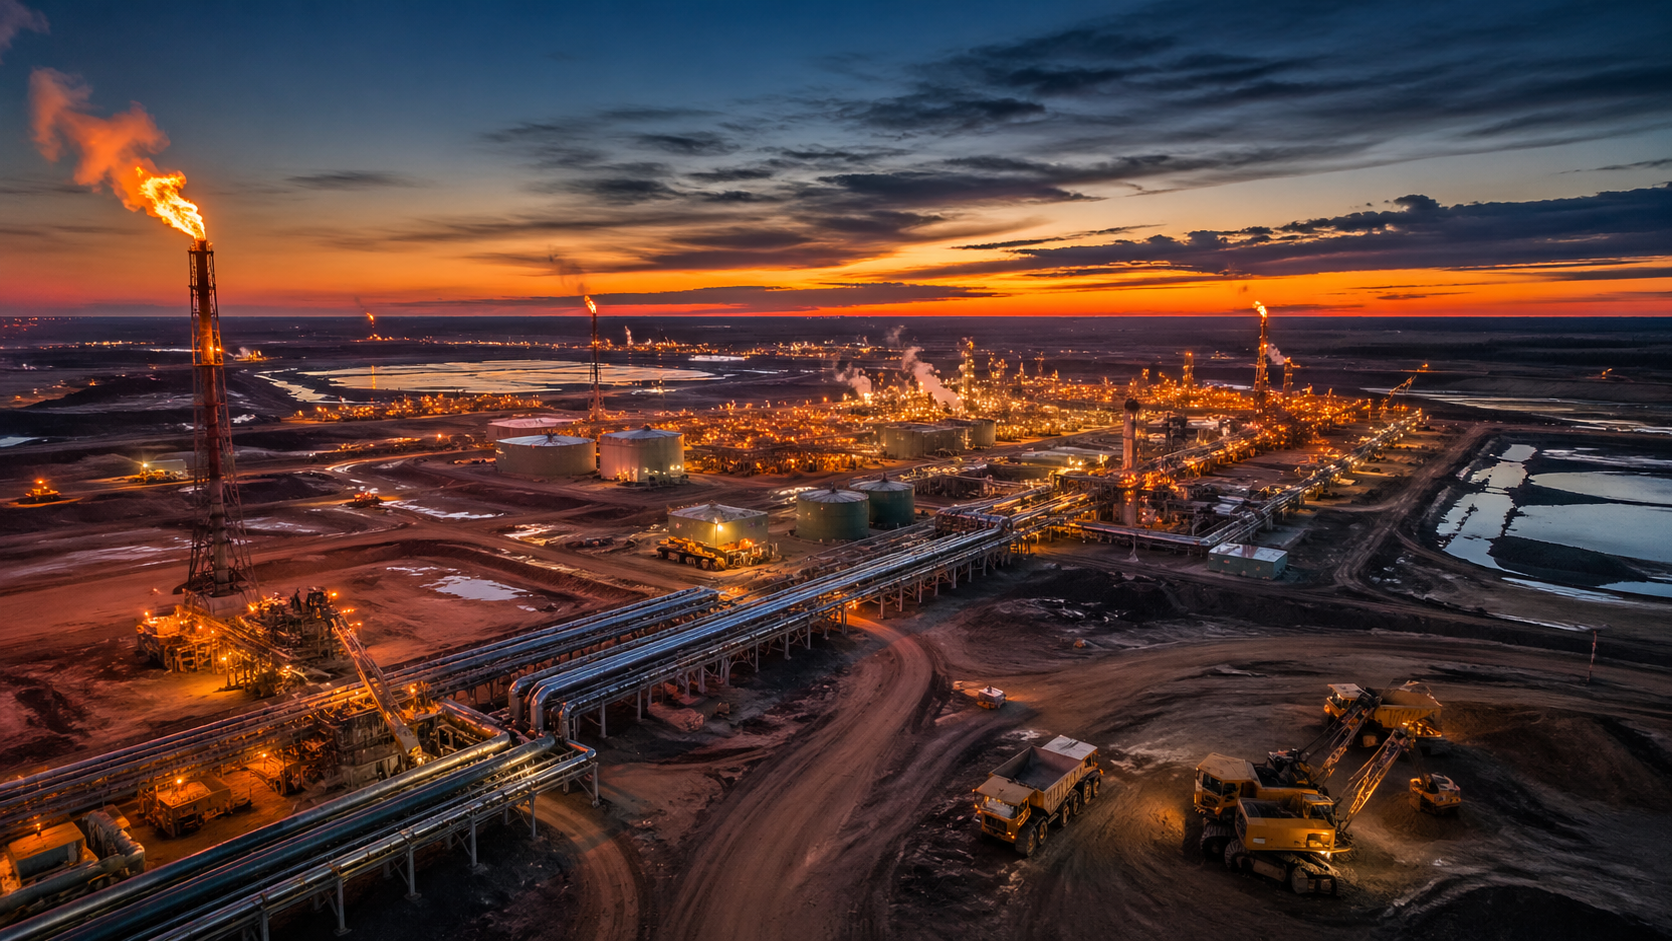
The five-to-six-week repair timeline on Saudi Arabia’s East-West pipeline is the most economically consequential data point for Canada this week beyond the Fed’s rate decision. At WTI above US$100 for six additional weeks — through the end of October — Canada’s oil export revenues will be substantially above any pre-conflict model. The Canada Energy Regulator’s data confirmed that Canadian crude oil exports reached CA$140 billion in 2025 at pre-conflict prices. At current prices — with WTI more than US$30 above pre-conflict levels — the incremental export revenue flowing to Canadian producers through this period is measured in billions of dollars. That resource income windfall partially offsets the economic damage from trade war tariffs in the manufacturing and agricultural sectors — but it also exacerbates the domestic inflation challenge that the Bank of Canada is managing without a rate response.
The September 29 Tariff Expansion Is Canada’s Next Formal Economic Inflection Point
Trump’s signing of tariff proclamations expanding restrictions on Canadian goods effective September 29 — targeting alcohol, motorcycles, dairy, paper, wood, aluminum, and furniture at 50% — is the next formal trade war escalation event with direct economic impact. Canadian producers in these sectors must begin adapting immediately: inventory decisions, pricing adjustments, supply chain redirection, and customer communication must all proceed now if they are to be ready for September 29. The Government of Canada’s CA$7.5 billion business support package provides partial mitigation, but the procurement of emergency loans and the implementation of sector relief programmes take time that the 14-day countdown does not fully allow.
Sector Breakdown
The economic impact of this week’s converging pressures sorts Canada’s sectors into clear categories. Energy — the largest beneficiary of the Saudi pipeline closure — is generating extraordinary free cash flow that improves corporate balance sheets, government royalty revenues, and Alberta’s fiscal position simultaneously. Manufacturing — facing the September 29 tariff expansion on aluminum, wood, and paper — is absorbing the most direct trade war economic damage, with Ontario and British Columbia manufacturing employment most at risk. Agriculture — with dairy specifically targeted in the September 29 tariff list — faces dual exposure: existing U.S. tariffs on Canadian agricultural exports and now higher Canadian costs on U.S. agricultural equipment under Canada’s retaliatory schedule. Consumer-facing sectors — facing diesel at all-time highs raising transportation costs for every product delivered by truck or rail — carry the most diffuse but pervasive cost increase of any sector in this week’s macro complex.
Also Read: Best long term Canadian stocks
Risks to Watch
The most consequential downside scenario for Canada’s economy is an FOMC dot-plot on Wednesday that signals multiple additional rate hikes in 2026 and 2027, combined with a sustained Saudi pipeline repair timeline of six weeks or longer. In that scenario, Canadian bond yields rise materially above current levels, the Canadian dollar faces additional downward pressure from the widening rate differential, and the one-third of Canadian mortgage holders facing renewal by year-end encounter a more hostile financing environment than even the current elevated rate levels imply. The September 29 tariff expansion — if responded to by the Trump administration with a further round of counter-measures — could trigger an escalation cycle that extends well beyond November’s midterm election marker. The AI slowdown signal, if it translates into reduced hyperscaler capital investment in 2027, would affect the technology-adjacent components of Canadian corporate earnings that have provided the most positive surprise of 2026.
What to Watch Next
Wednesday’s FOMC rate announcement and dot-plot at 2:00 p.m. ET is the week’s most important event for Canada’s economic trajectory through Q4. Saudi Aramco’s pipeline repair update — specifically whether limited operations can resume sooner than five weeks — will determine the duration of the energy price support for Canadian producers. September 29’s tariff expansion effective date is the next formal escalation event. Bank of Canada Governor Macklem’s Wednesday remarks will be the domestic policy update most relevant to Canadian households and businesses. November 3 U.S. midterms remain the earliest diplomatic restart marker for Canada-U.S. trade talks.
Final Outlook
Canada’s economy on September 15, 2026 is demonstrating the paradoxical resilience of a resource-exporting, financially sophisticated, rule-of-law economy under concentrated multi-directional stress. The Saudi pipeline closure is simultaneously an economic windfall for Canadian oil producers and an inflationary pressure on Canadian consumers. The Fed’s rate hike is simultaneously a challenge for Canadian mortgage holders and a possible currency stabiliser if the Canadian dollar strengthens on any oil-driven current account improvement. The trade war’s tariff escalation is simultaneously damaging manufacturing and providing a fiscal incentive to diversify supply chains in ways that may strengthen Canada’s long-term economic independence from the United States.
None of these paradoxes resolve neatly, and none should be dismissed as trivial. The week of September 15 — FOMC, Saudi pipeline, AI slowdown, September 29 tariff countdown — is the most complex single week of Canada’s 2026 economic experience. Its resolution, through Wednesday’s FOMC announcement and the days that follow, will define Q4’s starting conditions more completely than any prior event in the cycle.
Verdict: Neutral with sector-selective opportunities. Canadian energy producers capturing the Saudi pipeline closure premium and corporate names demonstrating quality earnings and capital management (Descartes, Franco-Nevada, Thomson Reuters) are the most defensible economic exposures in the current environment. Monitor Wednesday’s FOMC dot-plot, Saudi repair updates, and September 29 tariff implementation as the three most consequential near-term economic catalysts for Canadian market positioning.
Sign Up For our Newsletters to get latest updates